
Choosing a mortgage involves more than comparing interest rates. The type of loan you choose can affect your monthly payment, how predictable your housing costs are, and how the financing fits your plans for the property.
Two common options are a fixed-rate vs adjustable-rate mortgage, each with a different approach to interest rates and payments. Understanding how each works can help you compare your options based on how long you expect to own the home, how much payment predictability you want, and how comfortable you are with potential rate changes.
HOW DOES A FIXED-RATE MORTGAGE WORK?
A fixed-rate mortgage keeps the same interest rate for the full term of the loan. The principal-and-interest portion of your payment generally remains the same, although your total monthly housing payment can change if property taxes, homeowners insurance, or other costs change. In California, for example, 15- and 30-year terms are among the most common.
A shorter loan term generally means higher monthly payments but less interest paid over the life of the loan. A longer term generally spreads repayment over more years, reducing the monthly principal-and-interest payment.
Advantages of a fixed rate:
- Predictable principal and interest payments: Your rate does not change when market rates rise.
- Long-term stability: Consistent principal-and-interest payments can make long-term budgeting easier.
- Protection from rising rates: Future market increases do not change the interest rate on your existing loan.
What’s the tradeoff?
A fixed-rate loan can provide greater payment predictability, which may be especially valuable for buyers who expect to own the property for many years. The tradeoff is that the starting rate may be higher than some ARM options, so buyers should weigh predictable payments against their expected ownership period and overall financing costs.
HOW DOES AN ADJUSTABLE-RATE MORTGAGE WORK?
An adjustable-rate mortgage or ARM typically begins with an initial fixed-rate period. After that period, the interest rate can adjust according to the terms of the loan.
Before committing to a mortgage, make sure you know how it works and what you should expect for the duration of its term.
ARMs are commonly described with two numbers, such as a 5/1 or 7/1 ARM. The first number indicates how many years the initial rate remains fixed, while the second generally indicates how often the rate can adjust afterward.
A 5/1 ARM, for example, has a five-year initial fixed period followed by adjustments that typically occur once a year. The CFPB identifies three, five, seven, and 10 years as common initial fixed periods.
After the initial period, the new rate is generally calculated using an index plus a lender-set margin, subject to the loan’s adjustment caps. The index can change with market conditions, while the margin is established in the loan agreement.
Advantages of an ARM include:
- Lower initial rate: Some ARMs start below comparable fixed-rate loans.
- Potential short-term savings: A lower initial payment can reduce borrowing costs during the introductory period.
- Useful for certain ownership plans: The initial fixed period may align with a buyer’s expected time in the property.
What’s the tradeoff?
A lower starting payment can be useful, but buyers should consider whether the loan would remain affordable if the payment rises later. Review the maximum potential rate and payment and consider whether that higher amount would still fit comfortably within your budget.
FIXED-RATE VS. ARM: WHAT’S THE DIFFERENCE?
The main distinction in a fixed-rate vs adjustable-rate mortgage comparison is what happens to the interest rate after the loan begins.
| Factors | Fixed Rate | ARM |
|---|---|---|
| Interest rate | Remains fixed | Fixed initially, then may adjust |
| Payment predictability | Generally more predictable | Can change after the initial period |
| Initial rate | May be higher | May be lower |
| Exposure to future rate changes | Lower | Greater |
| Potential fit | Buyers seeking predictable payments | Buyers whose plans may align with the initial fixed period |
Neither structure automatically fits every buyer. The appropriate choice depends on the loan terms, expected ownership period, financial circumstances, and tolerance for potential payment changes.
WHAT ARE ARM RATE CAPS?
ARM rate caps limit how much the interest rate can change. They are an important part of understanding the potential range of future payments.
There are generally three types:
- Initial adjustment cap: Limits how much the rate can change when it first adjusts.
- Subsequent adjustment cap: Limits how much the rate can change at later adjustment periods.
- Lifetime adjustment cap: Limits how much the rate can change over the life of the loan.
For example, a 2/2/5 cap structure would generally limit the first adjustment to two percentage points, later adjustments to two percentage points each, and the total increase over the life of the loan to five percentage points. Actual caps vary by loan.
Caps limit potential changes, but they do not prevent an ARM payment from becoming substantially higher if rates rise.
WHICH MORTGAGE FITS YOUR PLANS?
Your expected ownership period is one factor to consider, but it should not be the only one.
A fixed loan may appeal to someone who values long-term payment predictability and expects to remain in the property for many years.
An ARM may warrant consideration if its initial fixed period aligns with a buyer’s plans, but buyers should not assume they will automatically be able to sell or refinance before the rate adjusts. The CFPB specifically recommends understanding the maximum potential rate and payment under the loan terms.
Consider questions such as:
- How long do you realistically expect to own the property?
- How would a higher mortgage payment affect your budget?
- Are you comfortable with potential payment changes after the initial fixed period?
- How much does the initial rate affect your purchase plans?
- What is the maximum rate and payment permitted under the loan?
- How do the loans compare when you consider both current and potential future costs?
SHOULD YOU CHOOSE A FIXED-RATE OR ADJUSTABLE-RATE MORTGAGE?
There isn’t a universal answer. The appropriate comparison depends on the relationship between the loan’s terms and your financial plans.
A buyer expecting to stay in a home for many years may place greater value on long-term payment predictability. Someone expecting to move within a few years may pay particular attention to the initial rate, the length of the fixed period, and the costs that could arise if those plans change.
The important step is to compare the loans based on their full range of potential costs rather than treating the initial interest rate as the deciding factor.
FREQUENTLY ASKED QUESTIONS
What is the difference between a fixed-rate and adjustable-rate mortgage?
A fixed-rate loan keeps the interest rate unchanged for the life of the mortgage. An adjustable-rate loan starts with a fixed period, after which the rate can change according to the loan’s terms.
Is a fixed-rate mortgage better than an ARM?
Neither option is automatically better for every borrower. The choice depends on factors such as how long you expect to own the home, your tolerance for payment changes, and the specific terms of each loan.
How long does an ARM stay fixed?
The initial fixed period of ARM depends on the loan. Common examples include 5/1, 7/1, and 10/1 ARMs, where the first number represents the number of years before the first adjustment.
Can an ARM interest rate go down?
Yes. Depending on the loan’s index, margin, and caps, the rate may increase or decrease when it adjusts. Some loans also limit how far the rate can fall.
Can you refinance an ARM into a fixed-rate mortgage?
Potentially. An ARM borrower may refinance into a fixed-rate loan if they qualify and the costs and terms make sense at the time. Refinancing is not guaranteed, and future interest rates and the borrower’s financial circumstances will affect the decision.
What should you consider before choosing an ARM?
Before choosing an Adjustable Rate Mortgage, look at the initial rate, length of the fixed period, adjustment schedule, index, margin, rate caps, maximum potential payment, and expected ownership period. Comparing these factors provides a clearer picture of how the loan could perform if rates change.
CHOOSE A LOAN THAT FITS WITH FREDY RODRIGUEZ REAL ESTATE
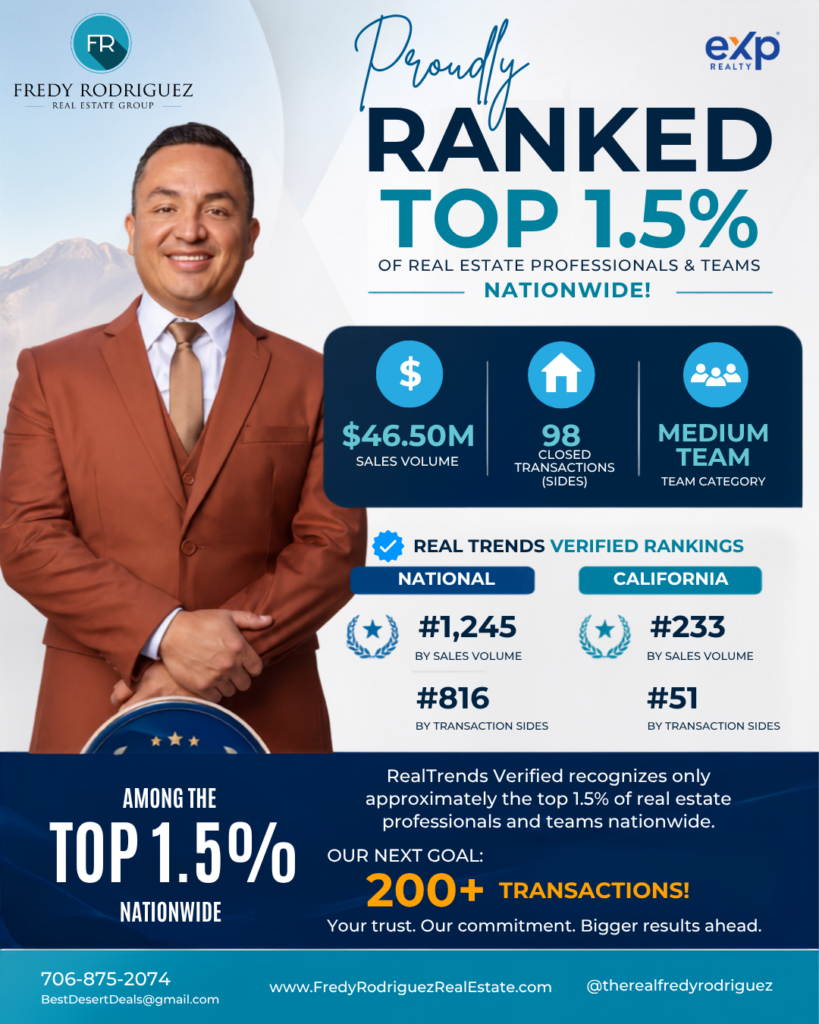

Top 1.5% Nationwide! 🏆 We’re officially RealTrends Verified among the top real estate professionals in the country. This achievement belongs to our amazing clients and the community who trust us with their home journeys every day. Thank you for your continued support!
The right mortgage depends on more than today’s rate. Your plans for the home, budget, and comfort with changing payments all deserve a place in the decision.
At Fredy Rodriguez Real Estate Group, we pair Coachella Valley market expertise with personalized guidance to help you evaluate homes and navigate the financing decisions behind your purchase.
Planning your next move? Gall 760.875.2074 or send a message to get started.